Fund accounting and payroll
Record restricted and unrestricted funds separately. Reconcile income and spending by grant or project and run payroll where included in your scope.
See how much of each grant is left to spend and what’s available for running costs. We help charities and community interest companies keep clear books and prepare for year-end reporting.
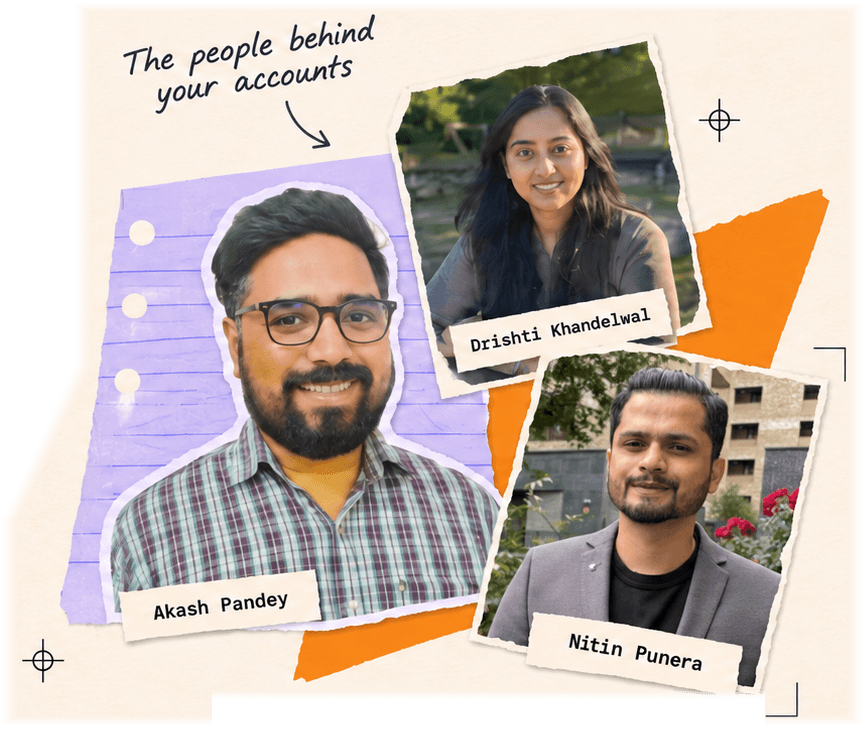
Your dedicated account managerBacked by an ACCA-qualified team
Akash Pandey, FCCACo-founder
Nitin Punera, ACCACo-founder
Trusted by UK businesses


Record restricted and unrestricted funds separately. Reconcile income and spending by grant or project and run payroll where included in your scope.
Help eligible organisations keep Gift Aid records and prepare claims. Prepare year-end accounts and support Charity Commission returns where required.
Prepare CIC accounts and help directors assemble the information for the annual CIC34 report. For charities, prepare records for your independent examiner or auditor when required.
| Grant received | £20,000 |
|---|---|
| Project delivery | (£8,250) |
| Project staff costs | (£4,500) |
| Grant funds left | £7,250 |
Tell us what you do, how you keep your records and which deadlines are coming up.
We agree what we’ll handle, what you’ll send us and when. You get a quote for that work.
We review your grant letters, fund balances and reporting deadlines. We also agree who signs off payroll, claims and filings.
We reconcile income and expenditure and report balances by fund or project. You can use those figures to brief trustees or directors and keep track of grant spending.
Community interest company supporting autistic people and their families.
Community interest company offering table tennis coaching and club sessions.
Start with bookkeeping and payroll. Add compliance, reporting or both, depending on what you need.
Base service
From £249 a month
Add to bookkeeping & payroll
£1,800 per year
Add to bookkeeping & payroll
£1,200 per month
For charities in England and Wales with financial years ending on or after 30 September 2026, gross income over £40,000 normally triggers an independent examination or audit. A charity audit is generally required if gross income exceeds £1.5 million, or if gross income exceeds £500,000 and gross assets exceed £5 million. Earlier financial years use different thresholds. Governing documents, funding terms and other legal requirements can also affect the decision. Charity Commission guidance on the threshold changes.
Gift Aid is available to eligible charities and community amateur sports clubs on qualifying donations. CIC status by itself does not make an organisation eligible. For eligible organisations we can help check donations against declarations and prepare claims. HMRC guidance on claiming Gift Aid.
The report covers how the CIC’s activities benefited the community and how it involved stakeholders. Directors also report relevant items such as director remuneration and certain transfers of assets. It goes to Companies House with the annual accounts. CIC Regulator’s CIC34 form and examples.
If you’re registered in England or Wales, you must report to the Charity Commission each year. What you submit depends on your income and legal structure. Charities registered elsewhere should check the requirements of their own regulator. Charity Commission annual return guidance.
Bookkeeping and payroll start at £249 a month. Compliance costs £1,800/year and reporting costs £1,200/month. Both are optional additions to bookkeeping and payroll.
Tell us what you need help with. We’ll reply within one working day.